US Stock Index Futures Gain as AI Rally Offsets Yield Concerns 2026
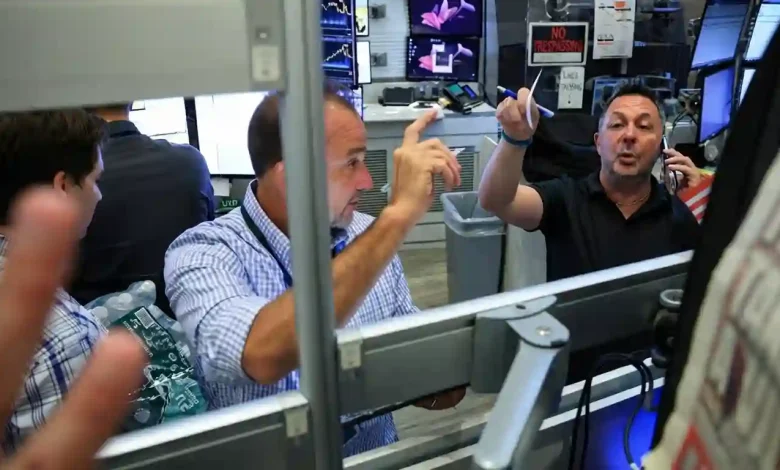
Table of Contents
US stock index futures rebounded across major exchanges on Friday morning as buoyant momentum across artificial intelligence hardware and semiconductor design firms neutralized lingering investor anxiety over heightened energy prices and sticky government bond yields. Institutional trading desks observed substantial risk appetite filtering through technology sub-sectors, sparked by robust forward-looking guidance and strategic infrastructure partnerships across enterprise compute suppliers. While portfolio managers maintain a watchful posture regarding potential diplomatic agreements designed to de-escalate Middle East friction, the prevailing sentiment in early New York trading highlighted the enduring strength of long-term technology investment themes.
Market Momentum: AI Optimism Drives Premarket Rebound
The broader benchmark contracts signaled a decisive opening advance following consecutive sessions characterized by cautious hedging and asset rotation. Similar to previous episodes where US stock futures climb amid expanding technology demand, Friday’s early price discovery process underscored resilient liquidity chasing growth equities. Contracts tied to the tech-heavy Nasdaq 100 outpaced those linked to the Dow Jones Industrial Average and S&P 500, indicating that institutional capital remains heavily skewed toward hardware manufacturers and software infrastructure innovators capable of defending operating margins regardless of cyclical crosscurrents.
Market participants who spent the preceding days processing sovereign debt volatility found fresh motivation in quarterly supply-chain metrics from regional and hyperscale chip vendors. The persistent deployment of generative computing frameworks across commercial logistics, medical diagnostic software, and financial platforms has prevented a broader tech sell-off, creating an institutional floor under premier equity contracts. Even as fixed-income instruments offer competitive yields, fund allocators continue prioritizing capital appreciation via high-margin technology leaders that operate outside the direct fallout of conventional industrial deceleration.
Semiconductor Sector Leads Premarket Advances
Semiconductor equities emerged as the unequivocal engine of Friday’s premarket resurgence, with frontline designers and fabrication architects recording widespread gains of more than 1%. Advanced Micro Devices (AMD) advanced firmly as market participants digested expanding adoption of its flagship enterprise accelerators across cloud networks, validating competitive performance benchmarks against legacy server components. Investors recognized that enterprise compute budgets are maintaining structural upward trajectories despite tighter corporate treasury policies elsewhere in the macroeconomy.
Marvell Technology (MRVL) mirrored that positive momentum, buoyed by expanding demand for bespoke data-center connectivity chips, optical interconnects, and cloud storage controllers essential for modern cluster processing. Concurrently, Cerebras Systems registered notable early bid volumes following strategic disclosures regarding its wafer-scale architecture installations across sovereign compute and commercial enterprise pipelines. Intel (INTC) also pushed into green territory, propelled by internal structural initiatives aimed at streamlining node deployment and expanding domestic packaging capacity. These coordinated advances correspond with wider movements observed across the broadcom AI chip supply chain, reaffirming that enterprise silicon demand continues to operate as the equity market’s primary shock absorber.
Megacap Tech Momentum: Tesla, Nvidia, and SpaceX
Beyond traditional fabless chipmakers, premier megacap balance sheets provided stable ballast for derivative contracts. Nvidia (NVDA) extended its winning trajectory, ticking higher in premarket sessions as ecosystem suppliers signaled stable component availability for its next-generation compute systems. Investment managers cited continuing capital expenditure allocations from mega-scale hyper-scalers as confirmation that artificial intelligence infrastructure spending will remain well-defended against broader macroeconomic hesitation throughout the fiscal year.
Tesla (TSLA) demonstrated solid upward momentum as retail and quantitative desks priced in expanding rollouts of proprietary vision algorithms and advanced autonomy capabilities. Furthermore, positive sentiment spilled into aerospace and orbital communications, where SpaceX (SPCX) contracts experienced buoyant trade following private market assessments of commercial satellite constellation performance and expanding payload delivery contracts. The concerted elevation of these industry leaders established an upward drift for contracts tracked on major indexes, echoing recent trading sessions in which U.S. stock index components demonstrated remarkable capacity to absorb negative macro headlines without experiencing systemic structural breakdowns.
Navigating Yield Pressure: Treasury Benchmark Trends
Despite the prevailing technology enthusiasm, bond market dynamics continue to impose tactical constraints on equity valuation multiples. The yield on the benchmark U.S. 10-year Treasury note hovered near pivotal technical resistance levels, reflecting sustained inflationary stickiness across domestic logistics networks and cautious Federal Reserve forward guidance. Heightened sovereign yields traditionally diminish the net present value of long-dated corporate earnings, making high-multiple tech shares vulnerable to abrupt corrections whenever borrowing benchmarks tick higher.
Traders across fixed-income desks note that persistent issuance volumes and robust domestic consumer expenditures have kept borrowing benchmarks elevated. When benchmark 10-year yields surge without warning, risk assets usually experience broad liquidation. However, Friday’s price action demonstrated that when corporate bottom lines demonstrate unambiguous fundamental growth, technology valuation multiples can decouple from traditional fixed-income gravity for prolonged stretches, maintaining investor demand across blue-chip equity derivatives.
Energy Complex Dynamics and Middle East Peace Hopes
The energy complex provided a complex backdrop to Friday morning’s trading environment, characterized by intense fluctuations across crude contracts. Elevated spot rates for fossil fuels have consistently threatened corporate margins over consecutive quarters, serving as an unwelcome variable for logistics corporations, manufacturing combines, and retail networks. Early trading desks remained exceptionally sensitive to diplomatic headlines, watching for signs that ongoing regional mediation might alleviate critical maritime shipping lanes.
Crude traders scrutinized updates regarding shipping corridors near vital waterways, including commercial passages across the Strait of Hormuz, where previous disruptions drove insurance premiums to historic extremes. Any verifiable reduction in maritime transit risk or diplomatic ceasefire agreement has the potential to compress crude spot contracts, diminishing headline inflationary inputs. Persistent fears of an acute oil supply crisis have previously suppressed consumer sentiment indices, making any substantive diplomatic progress a vital tailwind for broad equity valuation stability, particularly for cyclical consumer discretionary and transportation sectors.
Premarket Index and Equities Performance Summary
The following performance breakdown outlines the price dynamics across core index futures, leading semiconductor equities, and notable megacap names during early New York morning trade:
| Asset / Index | Ticker / Symbol | Premarket Movement | Primary Market Catalyst |
|---|---|---|---|
| Nasdaq 100 Futures | NQ | +0.65% | Semiconductor leadership and enterprise AI compute momentum |
| S&P 500 Futures | ES | +0.38% | Balanced technology gains overcoming energy input fluctuations |
| Dow Jones Futures | YM | +0.18% | Industrial stability tempered by elevated 10-year yields |
| Advanced Micro Devices | AMD | +1.42% | Expanding data-center architecture adoption and cloud enterprise contracts |
| Marvell Technology | MRVL | +1.28% | Accelerated high-speed data transmission demand and optical hardware sales |
| Intel Corporation | INTC | +1.05% | Foundry restructuring plans and domestic production capacity execution |
| Tesla Inc. | TSLA | +0.85% | Autonomous software deployment progress and delivery outlook optimism |
| Nvidia Corporation | NVDA | +0.72% | Unabated hyper-scaler capex forecasts and supply chain normalization |
Institutional Perspectives: Valuation Risk vs Earnings Growth
Institutional portfolio allocators entering the final trading session of the week find themselves navigating a classic late-cycle conundrum: historically elevated technology valuation multiples clashing with undeniable secular earnings expansion. When geopolitical conflict threatens supply chains and pushes energy rates higher, equity analysts routinely model downside margin revisions. Previous market episodes demonstrated how quickly futures slip as S&P 500 components retrace due to combined pressure from sovereign debt auctions and crude spikes.
However, the rapid monetization of enterprise computing software has created unique earnings defensiveness for specific mega-cap firms. Corporate executives across Fortune 500 enterprises continue to protect artificial intelligence investment budgets, treating computational infrastructure as an operational imperative rather than discretionary overhead. Consequently, asset managers are selectively deploying capital into companies possessing proprietary software ecosystems, clear pricing power, and dominant semiconductor market shares. This targeted capital allocation shields core technology components from broad cyclical downdrafts, allowing market participants to view commodity rallies as transient headwinds rather than permanent obstacles to capital compounding.
Key Macroeconomic Catalysts Ahead
Looking beyond the immediate Friday opening bell, trading desks are calibrating exposure models ahead of upcoming economic reports, notably personal consumption expenditure figures and regional manufacturing indices. If energy contracts experience sustained upward pressure and Brent crude oil prices remain firmly above historical averages, monetary policymakers may be forced to prolong their restrictive posture, postponing anticipated interest rate reductions well into future fiscal quarters.
Equity strategists stress that while artificial intelligence innovations offer exceptional long-term productivity enhancements, broader macroeconomic stability depends on orderly debt markets and normalized commercial trade routes. A conclusive breakthrough in Middle East peace negotiations would immediately relieve global transport networks, reduce shipping container rates, and provide an unambiguous catalyst for broad equity expansion. Until such geopolitical clarity emerges, equity futures will likely remain defined by a constructive tension between powerful technology-led rallies and the sober constraints imposed by global commodity markets and sovereign interest rate structures.

One Comment