Chinese Regulators Freeze Humanoid Robot IPOs Over Valuations 2026
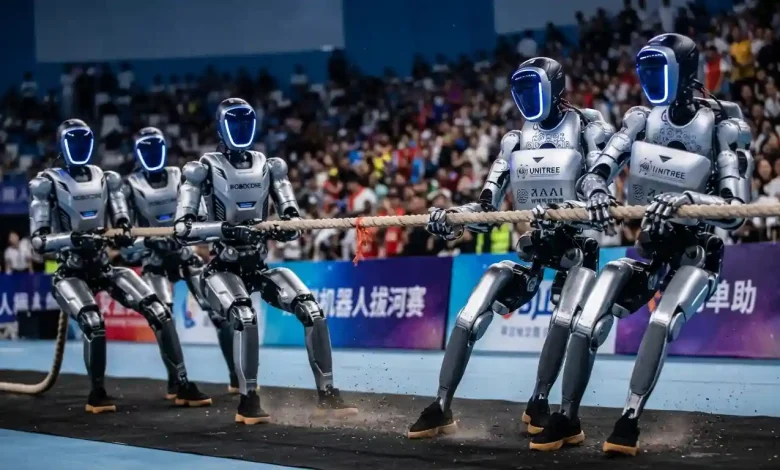
Table of Contents
Chinese regulators have initiated an aggressive campaign to rein in a speculative flood of initial public offerings from domestic humanoid robotics manufacturers, according to individuals familiar with regulatory proceedings in Beijing and Shanghai. The intervention marks a sharp recalibration by supervisory authorities who are scrutinizing whether surging private valuations and revenue figures disproportionately fueled by state-directed procurement contracts reflect viable, organic commercial adoption or an unsustainable technology bubble.
The supervisory freeze was precipitated by the volatile public listing of Unitree Robotics on Shanghai’s STAR Market. Following an explosive debut where shares expanded fivefold, market dynamics reversed violently, precipitating a steep 55% drawdown from historical peaks. This market turbulence demonstrated the acute peril facing retail investors when early-stage deep tech ventures access public capital before establishing predictable, high-margin cash flows outside government research allocations.
Chinese Regulators Intervene in the Humanoid Robot Market
Regulatory bodies including the China Securities Regulatory Commission (CSRC) and listing committees across domestic bourses have systematically expanded disclosure requisites for embodied intelligence and robotics hardware enterprises. The core concern rests upon the sudden proliferation of pre-profit ventures attempting to capitalize on industrial policy incentives without having developed mature mass-manufacturing pipelines.
Officials have historically utilized specialized listing venues to support national self-reliance initiatives in advanced technology. However, the current supervisory posture reflects a calculated effort to prevent speculative mania from distorting market capital allocation. As financial authorities monitor national economic stability alongside broader indicators like how Chinas economy slows to 4 3 in q2 despite export shifts, maintaining listing discipline on innovation boards has become a vital macroprudential priority.
The Unitree Robotics Precedent: From Market Sensation to 55% Slump
Unitree Robotics, widely recognized for developing agile quadruped platforms and lightweight bipedal humanoids, became the bellwether for the domestic robotics equity pipeline. The company captured widespread attention when its initial public offering witnessed an unprecedented buying frenzy, driven by retail optimism and institutional indexing requirements.
The trajectory began shifting rapidly following its listing. While initial coverage highlighted that unitree stock surges 460 during euphoric opening trades, the absence of sustained commercial purchase orders from the private enterprise sector quickly chilled secondary market enthusiasm. As institutional lockup provisions loomed and short-term speculative capital exited, the stock shed more than half its value from its record highs, triggering immediate alerts across regulatory trading surveillance desks.
This severe valuation contraction highlighted systemic risks regarding product differentiation. Although the company announced significant architectural milestones as unitree robotics shifts to mass market humanoids g1 and h1 models, market analysts questioned whether unit production volumes could translate into positive operating margins when confronted with soaring component costs and intense domestic price wars.
State-Backed Subsidies vs Commercial Viability: The Revenue Dilemma
Central to the current regulatory inquiry is the compositional integrity of applicant revenue sheets. Regulators are actively auditing customer lists to determine the true proportion of recurring commercial demand versus non-recurring state patronage. Many aspiring IPO candidates have demonstrated remarkable top-line growth over recent quarters, but forensic review reveals that a substantial volume of delivered hardware went directly into municipal demonstration projects, state-owned educational facilities, and subsidized regional robotics research centers.
Such revenue channels present substantial headwinds for long-term equity valuation. Demonstration initiatives frequently operate on one-off fiscal grants rather than perpetual procurement cycles. Furthermore, public perception and institutional credibility in the sector previously weathered reputational strain following incidents such as the academic misrepresentation the galgotias unitree robot scandal, which revealed how institutions occasionally deploy commercial hardware merely for demonstration optics rather than genuine functional integration.
Valuation Foam and Structural Imbalances in Robotics Hardware
Private funding rounds over the preceding eighteen months awarded unicorn valuations to domestic robotics firms that had delivered fewer than several hundred functional humanoid units. These multiples reflected pricing frameworks typical of pure software or cloud enterprise ventures rather than high-capital-expenditure hardware manufacturing operations.
The intense race for tech supremacy in the broader ai race with china exacerbated this capital distortion. Early-stage venture funds, anxious to secure stakes in national champion enterprises, bid up series funding rounds without demanding strict unit economics or commercial gross margin thresholds. When these balance sheets arrive before public exchange listing committees, the stark divide between private venture expectations and public market realities becomes unsustainable.
Comparative Analysis: Robotics Enterprise Performance & IPO Outlook
The following table outlines the structural contrast between enterprise-scale production realities and market valuation dynamics across the broader domestic hardware technology landscape.
| Company / Segment | Core Product Architecture | Primary Revenue Driver | Listing Status / Regulatory Trajectory | Key Valuation Vulnerability |
|---|---|---|---|---|
| Unitree Robotics | Bipedal Humanoid & Quadruped Platforms | Government Labs, Academic Institutes, Prototyping | Listed (STAR Market); Down 55% from peak | Limited non-subsidized commercial adoption |
| Industrial Robotics Peers | Articulated Robotic Arms, Automated Guided Vehicles | Automotive, Solar, Electronics Factory Assembly | Mature Listings / Traditional Boards | Cyclical capital expenditure slowdowns |
| Pre-IPO Humanoid Startups | Full-Scale Embodied General-Purpose Bipeds | Municipal Pilot Programs & Regional Tech Showcases | IPO applications paused or under forensic audit | High bill of materials (BOM), negative operating cash flows |
| Component Specialists | Harmonic Reducers, Planetary Rollers, Servo Motors | Supply sales to Tier-1 robot assemblers | Varying IPO stages across domestic venues | Customer concentration risk, fierce margin competition |
Impact Across Advanced Manufacturing and Component Suppliers
The regulatory cooling effect extends far beyond assembly firms to impact the entire upstream supply ecosystem. Specialized component manufacturers—producing precision strain wave gears, brushless DC motors, and multimodal sensory integration units—had aggressively expanded their own capital expenditure plans based on speculative humanoid order projections.
Major industrial conglomerates and contract manufacturing giants that monitor precision assembly trends, such as supply chain planners following the foxconn q3 outlook, are re-evaluating production schedules. If assembly startups cannot tap public capital markets to finance component inventories, component suppliers will face delayed payments, inventory write-downs, and curtailed research budgets. This ripple effect threatens to stall actual physical advancements in actuator efficiency and planetary roller screw manufacturing.
Institutional Chill: What the Listing Pause Means for Venture Capital
The freeze introduces severe liquidity complications for institutional investors. Venture capital and private equity vehicles that entered early funding rounds at elevated valuations now face prolonged hold periods. With the domestic initial public offering window abruptly restricted, fund managers cannot generate returns or return capital to limited partners via conventional stock market listings.
This development parallels the strategic restructuring seen in other major Chinese commercial listings. Market operators recall the procedural delays surrounding consumer retail titans, such as when shein hong kong ipo efforts encountered extensive cross-border regulatory compliance reviews and valuation calibrations. Similarly, advanced tech listings must increasingly navigate rigorous state expectations before proceeding. As alternative international listing pathways also encounter geopolitical frictions—mirrored across global markets in events like the planned kioxia us listing—domestic hardware innovators find their liquidity horizons significantly extended.
Reassessing Commercial Metrics: The New Listing Bar for Embodied AI
To secure listing approvals moving forward, robotics applicants must adapt to elevated supervisory standards. Regulatory authorities are signaling that future IPO candidacies will hinge upon demonstrable product utility in unstructured, open-market environments. Companies will be required to furnish auditable evidence of repeat enterprise contracts, gross margins independent of regional tax credits, and clear technological defensibility in core software stack development.
Market participants anticipate a wave of consolidation across the sector. Weaker startups unable to prove commercial viability outside municipal showcases will likely be absorbed by established industrial conglomerates or forced into down-rounds. While this regulatory reset slows near-term liquidity, institutional economists assert it will establish a much healthier foundation for China’s embodied intelligence ecosystem over the coming decade by prioritizing durable technological substance over transient financial speculation.
References & Authority Citations: