Fashion calendar disruption: How Hot Climates Hit Luxury Winter Margins 2026
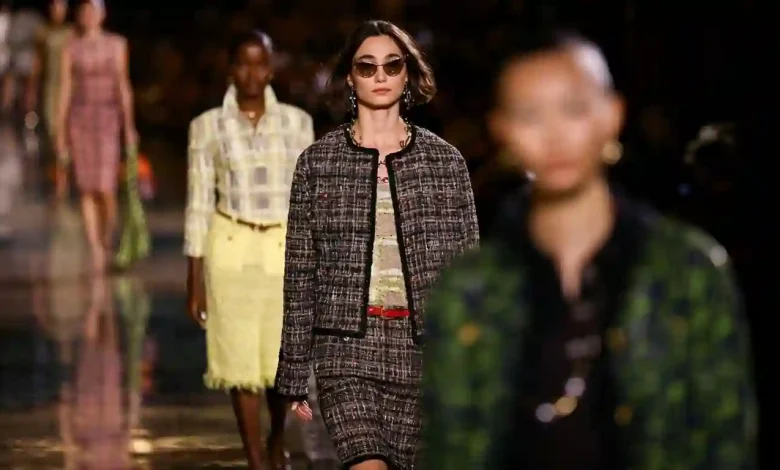
Table of Contents
Fashion calendar disruption has emerged as one of the most destabilizing operational challenges facing the global luxury apparel market. For well over a century, the high-end apparel trade structured its entire commercial machinery around a four-season cadence, placing an outsized financial bet on autumn and winter. The logic was mathematically sound: heavier coats, cashmere knits, leather boots, and shearling jackets carry significantly higher price points and superior gross margins compared to lightweight summer attire. As autumn approached, consumers routinely refreshed their cold-weather wardrobes, generating the windfall of revenue that underpinned annual operating profit across department stores, independent multi-brand boutiques, and luxury flagship networks.
However, global climate volatility and unprecedented heat waves extending deep into October and November have completely severed the connection between delivery schedules and meteorological reality. High-end department stores and multi-brand boutiques receive thick wool outerwear and heavy shearling in July and August, when ambient temperatures in major retail hubs like New York, Milan, Paris, and Shanghai frequently exceed 90 degrees Fahrenheit. Because shoppers naturally defer purchases of heavy cold-weather garments until the thermometer drops, luxury brands face stagnant floor traffic and delayed conversions, complicating planning alongside shifting consumer spending metrics across worldwide commercial sectors.
The Breakdown of Autumn and Winter Primacy
The traditional fashion system was engineered during an industrial era characterized by stable, predictable climate rhythms. Under this orthodoxy, design studios would present Autumn/Winter collections on runways in February and March, commence factory manufacturing through the spring, and ship dense woolens, quilted parkas, and lined trench coats into boutiques by late summer. The expectation was that by late September, crisp weather would generate urgent consumer demand, clearing inventory at full retail markup well before holiday gift-buying gained momentum.
Today, that seasonal correlation has disintegrated. Subtropical autumns have turned high-density woolen displays into visual liabilities. Merchandisers report that when storefront windows and luxury shopping floors showcase heavy shearling coats during unseasonably sweltering Indian summers, consumers experience cognitive dissonance. Foot traffic simply walks past coats priced upwards of five thousand dollars because the immediate utility of the garment is zero. This psychological disconnect compresses the selling window for premium outerwear from sixteen weeks down to a frantic four-to-six-week period between late November and early January.
Economic Pressures on High-Margin Cold-Weather Lines
Outerwear and tailored tailoring represent the primary profit engine of prestige apparel conglomerates. Unlike basic tees or summer linen shirts, which battle fierce price compression, luxury wool coats and technical parkas support tremendous gross margin architecture. The materials, structural canvas, lining, hardware, and specialized artisan labor justify prices that can easily yield gross margins north of 65 to 75 percent. When outerwear underperforms, the entire corporate balance sheet absorbs the impact.
The compounding risk involves the carrying cost of inventory. Bulky winter garments consume immense physical footprint across global logistics fulfillment hubs, boutique backrooms, and regional distribution networks. Storing voluminous puffers, long coats, and dense knitwear inflates warehousing expenditure. As holding times extend due to delayed consumer interest, working capital remains locked inside inventory that depreciates in perceived novelty with every passing week, mirroring challenges seen when broader retail economic headwinds alter store traffic patterns.
Margin Erosion and the Retail Markdown Dilemma
When high-ticket inventory fails to turn over by mid-November, wholesale accounts and independent stockists face acute cash-flow strangulation. Multi-brand retailers operate on tight credit lines that require rapid liquidation of seasonal orders to finance Spring/Summer consignments. Consequently, stores initiate steep price promotions far earlier than historical norms, slashing tags by 30 to 50 percent just as cold temperatures finally arrive in December.
This premature discounting cycle trains consumers to never pay full retail price for cold-weather luxury apparel. Sophisticated shoppers now deliberately delay purchasing designer trench coats and wool overcoats, confident that unseasonably warm autumns will force department stores into promotional markdowns before winter weather sets in. The resulting margin erosion destroys profitability for wholesale partners and diminishes the prestige value of heritage brands that depend upon full-price sell-through to maintain scarcity value.
Luxury Maisons Pivot Away From Rigid Seasonality
In response to persistent climate headwinds, marquee houses are rewriting their creative blueprints. Rather than crafting collections around heavy alpine motifs and monolithic wool blankets, creative directors are emphasizing “seasonless” aesthetics. Wardrobes are increasingly designed with modularity in mind, allowing individual pieces to function fluidly across wildly disparate temperatures.
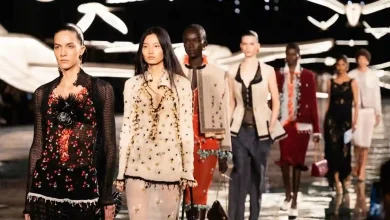
This aesthetic transition is evident across major international fashion capitals. Designers who previously built their reputations on rigorous winter tailoring are integrating ultra-fine merino wools, breathable unlined suiting, and convertible outerwear with detachable thermal linings. Notable developments seen during recent runway presentations such as Chanel S/S 2027 highlight how leading design houses are calibrating silhouettes to withstand erratic microclimates without surrendering luxury allure.
Runway Realism Versus Traditional Delivery Timelines
The gap between runway fantasy and retail reality has forced a profound rethink of delivery calendars. Forward-thinking executive teams are demanding that merchandise arrive in stores in synchronicity with regional climate data rather than adherence to an outdated Parisian calendar. Rather than dropping heavy wool coats in July, advanced retail operators are breaking shipments into granular micro-phases.
Lightweight transition garments—such as silk-blend cardigans, open-weave blazers, and compact poplin shirts—are now slated for August and September delivery, alongside transitional street style trends that prioritize versatile layering. Dense knitwear, cashmere overcoats, and down-filled outerwear are pushed back to October and November release schedules, aligning floor arrivals with the actual onset of sub-fifty-degree weather.
Material Science and the Rise of Year-Round Layering
The imperative to navigate hotter autumns is sparking an unprecedented wave of textile engineering. Heritage fabric mills across Biella, Italy, and Yorkshire, England, are working closely with luxury conglomerates to produce textiles that deliver the visual density and draping of traditional winter fabrics while maintaining thermal breathability.
Tropical-weight worsted wools, micro-perforated double-faced cashmeres, and silk-wool blends have largely supplanted rigid 600-gram melton wools. These high-performance luxury textiles enable brands to retain the refined aesthetic of classical tailoring, reinforcing the ongoing evolution of luxury tailoring across European powerhouses. Consumers can wear these garments comfortably in an air-conditioned office or on an unseasonably warm city street without experiencing thermal distress.
Comparative Analysis: Traditional vs. Climate-Adaptive Delivery Models
The shift away from legacy apparel merchandising models is illustrated by the timing, financial allocations, and product mixes adopted by global luxury houses adapting to prolonged warm seasons.
| Merchandising Dimension | Traditional Fashion Calendar | Climate-Adaptive Delivery Model | Operational & Financial Impact |
|---|---|---|---|
| Autumn/Winter Shipments | July – August (Heavy Drops) | September – November (Staggered Drops) | Eliminates early dead-stock holding costs; synchronizes supply with consumer weather demand. |
| Outerwear Fabric Weight | Heavyweight Melton / 500-700 gsm | Mid-to-Lightweight Technical / 250-400 gsm | Enhances multi-climate versatility; broadens global market applicability across warm zones. |
| Outerwear Gross Margin Risk | High Markdown Risk (30-50% cuts) | Controlled Full-Price Sell-Through (0-15% cuts) | Protects operating margins and preserves luxury brand equity by eliminating panic sales. |
| Core Merchandising Philosophy | Rigid 4-Season Binary (SS / AW) | Fluid Seasonless & Layering Architecture | Encourages year-round basket size consistency and reduces working capital volatility. |
| Wholesale Payment Cycle | Standard 30-60 day terms post-July | Performance-linked milestone deliveries | Eases liquidity pressure on independent multi-brand boutiques and specialty retailers. |
Supply Chain Bottlenecks and Excess Inventory Liabilities
The friction caused by delayed autumn demand radiates down the entire manufacturing pipeline. When finished garments sit idle on retail racks, downstream purchase orders for subsequent collections are delayed or reduced. Raw material suppliers, weaving mills, and finishing ateliers experience unpredictable production halts, making steady labor and capacity planning nearly impossible.
Furthermore, unsold high-end winter inventory creates severe sustainability liabilities. Luxury houses are legally prohibited or brand-constrained from dumping excess merchandise into off-price discount channels without eroding their brand cachet. In an era where corporate responsibility disclosures are scrutinized by institutional investors, sitting on thousands of unsold down jackets and tailored overcoats represents both an environmental and economic hazard. Brands are increasingly forced to redesign supply contracts, reconfigure manufacturing runs, and embrace smaller initial order volumes to mitigate overproduction risk.
Drop Models, Merchandising Pivots, and Regional Nuance
To overcome the rigidity of the traditional calendar, top-tier brands are adopting direct-to-consumer drop strategies borrowed from streetwear, while investing heavily in regional market customization. Rather than shipping a standardized global assortment to every flagship, brands are utilizing hyper-localized climate data to dictate allocation. While a flagship in Northern Europe may still receive cold-weather knitwear in October, a counterpart boutique in Southern Europe, the Middle East, or the Sun Belt of the United States receives lightweight silk-wool blends and transitional parkas.
This operational agility is driving corporate adjustments within corporate flagships, influencing decisions behind retail footprint expansion in key global metropolitan areas. Maisons are also emphasizing historical trench coats and unlined macs, celebrating trench coat craftsmanship that provides water resistance without trapping excessive body heat. Meanwhile, independent luxury houses highlighted in contemporary designer collections are demonstrating that tailored suiting made from open-weave twills can replace heavy overcoats as the primary statement purchase of the autumn wardrobe.
Long-Term Commercial Outlook for Luxury Retailing
As meteorological records continue to be broken globally, fashion’s legacy calendar will inevitably be discarded entirely. The industry is moving decisively toward continuous, dynamic inventory flows where the concept of Autumn/Winter and Spring/Summer exists largely as creative branding rather than logistical prescription. The houses that thrive in this emerging reality will be those that master flexible manufacturing, invest deeply in thermodynamic fabric technology, and align their retail operations with real-time climatic shifts rather than antiquated fashion-week schedules.
Ultimately, the disruption of the fashion calendar exposes a fundamental truth about modern commerce: consumer behavior is inexorably tethered to physical comfort. No amount of runway glamour or marketing spend can force a shopper to invest thousands of dollars in a heavy cashmere overcoat while walking under an eighty-degree autumn sun. By accepting climate realities, luxury brands have the opportunity to build more sustainable, margin-resilient, and customer-centric businesses that thrive regardless of what the thermometer reads.